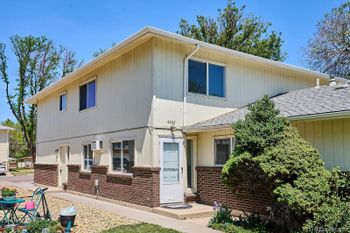
$257,900
Active
2
Beds
1
Baths
922
Sqft
0.01
Acres
7309 W Hampden Ave #4802, Lakewood, CO 80227
MLS#: 2133233
Rent to own homes in Lakewood are private lease options between a buyer and a seller; the City of Lakewood has no rent-to-own program and no down payment program of its own. As of October 25, 2026, 2 of the 434 Lakewood homes for sale mentioned rent to own, a lease option or seller financing in the MLS remarks, so the grid below shows Lakewood homes for sale now. Jefferson County points buyers to metroDPA, and a 620 score may let you buy today.
Get rent-to-own and low-down-payment homes in Lakewood sent to you. Call or text 303-955-4220. A live person answers.
Send me the Lakewood listWhat it’s like to live in Lakewood: our Lakewood area guide.
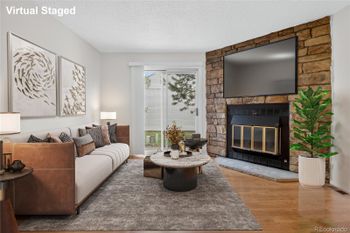
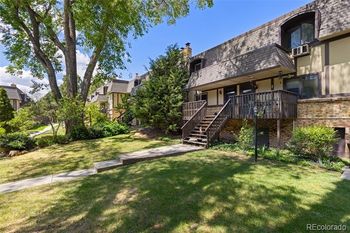
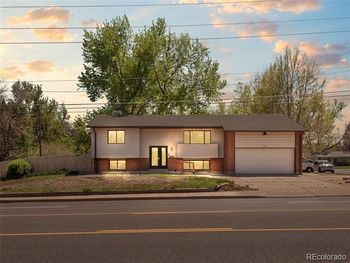
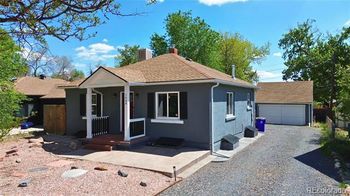
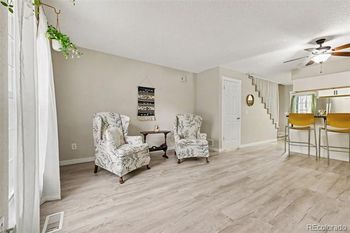
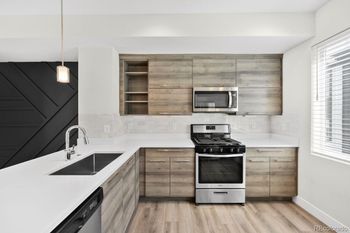


Lakewood is close to an even split: 41.9% of homes are rented, and the Census median value is $574,400. For a renter there, lease to own in Lakewood is worth its fee only when a mortgage is 12 to 24 months away. The Kenna Group at Keller Williams DTC asks every Lakewood caller what has them looking at rent-to-own instead of buying, because the answer changes the plan.
620+
You may not need rent-to-own. metroDPA (the program Jefferson County lists) and CHFA can cover the down payment. Next step: a pre-approval call with a lender of your choice.
580 to 619
Buy with your own down payment. 580 is the FHA minimum with 3.5% down, about $20,125 on a $575,000 Lakewood home. Most down payment assistance programs we work with start at a 620 credit score, so this path uses your own savings.
Under 580
Work on credit first. A lender call will not help yet. Pull your free reports at annualcreditreport.com and ask us about the Kenna Credit Care program; we call back when the score is ready.
| Rent to own (lease option) | Buy now with down payment assistance | |
|---|---|---|
| Cash up front | Option fee, often 1% to 5% ($5,750 to $28,750), lost if you do not buy | CHFA asks for at least $1,000 of your own money; metroDPA has no minimum investment; the seller credit sets the rest |
| Credit | Set by each seller; you still need a mortgage when the lease ends | 620 for most assistance; 580 with your own 3.5% FHA down payment |
| Who owns the home | The seller, until you close | You, at closing |
| Equity while you wait | Only the rent credits the contract allows | All of it, from day one |
| Which homes | Only homes whose sellers agree to a lease option | Any Lakewood home for sale: the whole grid above |
The $575,000 example matches the Census median Lakewood value ($574,400); today’s average list price is $570,000. Second loans from CHFA and metroDPA carry no monthly payment and are repaid when you sell, refinance or pay off.
Renting versus owning in Lakewood: the Census Bureau’s 2020-2024 survey shows a median Lakewood rent of $1,806 and a median owner cost with a mortgage of $2,330, a $524 monthly gap.
Checking a Lakewood seller: Lakewood is in Jefferson County. The county’s property records search shows the owner, and its recorded documents search shows deeds of trust and liens. Check both before you pay an option fee.
434
Lakewood homes for sale, active or coming soon, October 25, 2026
158
of them listed at $400,000 or less
2
mention rent to own, a lease option or seller financing in the MLS remarks
The 2026 Jefferson County loan limit is $862,500 for conforming and FHA loans. Starter search: affordable homes for sale in Lakewood, with the HOA on every tile.
No. Neither the City of Lakewood nor Metro West Housing Solutions runs one. A Lakewood lease option is a private contract, so a Colorado real estate attorney and a recorded memorandum of option are your protection.
On October 25, 2026, 2 of the 434 Lakewood homes for sale mentioned rent to own, a lease option or seller financing in the remarks. Most Lakewood lease options come from asking sellers directly.
Lakewood has no city program. Jefferson County points to metroDPA, and CHFA works statewide. Both start at a 620 credit score and need a homebuyer class.
Look the address up in Jefferson County’s property records search, then search the county’s recorded documents for deeds of trust, liens or a notice of default. A seller behind on the mortgage can lose the home, and your option with it.
Census 2020-2024 figures put the median Lakewood rent at $1,806 and the median owner cost with a mortgage at $2,330. A rent-to-own deal adds an option fee and often a rent premium on top of the rent.
Next steps: Lakewood homes for sale · CHFA down payment assistance · the $1,000 cash-to-close path · mortgage pre-approval · first-time buyer guide · Denver rent to own homes · Wheat Ridge rent to own homes · Golden rent to own homes · all Colorado rent to own homes · our Lakewood area guide.
Call or text 303-955-4220. A live person answers.
Browse Available Homes
Rent-to-own in Lakewood is real, and it is smaller than the search results suggest: the national programs have pulled back, so the deals that work are private lease-options with individual Lakewood sellers, mostly on homes that have sat 45 days or more. On October 25, 2026, 2 Lakewood homes carried a rent-to-own, lease-option or seller-financing note in the MLS; the rest of the list is built by asking. Below: the requirements, the costs, the Colorado contract rules, the red flags, the other Front Range cities, and the buy-now path.
The deal
1 to 3 years
Option fee of 1 to 5 percent up front, part of the rent credited to the purchase.
What sellers want
580 to 620
No eviction or bankruptcy in the last two years. Below 580, a 12-month repair plan first.
The alternative
3.5% down
Many rent-to-own shoppers can buy today. A live person runs both numbers.
The rule
Attorney + recorded
Colorado has no rent-to-own statute; the contract is the protection.
Most people searching for rent-to-own in Lakewood can buy a home now. A 620 credit score qualifies for Colorado down-payment assistance, and a participating lender can run a program that brings the buyer’s cash to close to about $1,000: the down payment comes from the assistance, the closing costs come from the seller credit, and you keep the money a rent-to-own seller would have taken as an option fee. There is a second saving nobody mentions: the first mortgage payment is not due until the first of the month after the month you close, so a buyer who closes early in the month skips close to two months of rent on the way in.
A rent-to-own search in Lakewood is a buyer with a reason: not enough saved, a score under 620, student loans, a job that started last month, a short sale in the past. With 171 of Lakewood's 490 listings under $475,000, every one of those reasons has a cheaper answer than a lease-option. The numbers below run on the median Lakewood home, $540,000, with a 30-year FHA loan.
Every Lakewood home for sale: Lakewood homes for sale. Call or text 303-955-4220. A live person answers.
In Lakewood the down payment on the median home is $18,900 with FHA, and CHFA covers it: a 3 percent grant ($15,633) that is never repaid, or a 4 percent second mortgage at 0 percent. The seller pays closing costs through the offer. You bring about $1,000. Rules on CHFA down payment assistance, the example on $1,000 cash to close.
580 is the FHA floor with 3.5 percent down, so a 590 buys a Lakewood home today without any assistance. Under 580, paying every card under 30 percent of its limit and disputing errors moves most scores 20 to 40 points in 60 days: credit care. The homes: all Lakewood homes for sale.
Debt ratios kill fewer Lakewood files than renters expect: FHA allows 50 percent of income to all payments, CHFA 50 to 55. Student loans on income-based plans count at the plan payment. The exact ratio for your income is on mortgage pre-approval.
New job, same line of work: an offer letter and a pay stub are enough. Self-employed less than two years is the one that waits. Start on mortgage pre-approval.
Waiting periods, not bans: three years after a foreclosure, two after a Chapter 7, one year into a Chapter 13. If the date is inside two years, a lease-option on a Lakewood home gets you in now; the rest is on after a foreclosure.
Rent-to-own fits exactly this: a Lakewood home you want, two years to decide, and only the option fee on the line. Compare the neighbors first: Wheat Ridge, Denver, Arvada, Englewood.
No credit check and a few hundred dollars down is how Lakewood renters lose option fees. A legitimate lease-option is written by a lawyer, recorded, and sits on a home with no default. Red flags are below.
Sellers price a two-year lock above the market. Taking over a seller's 3 percent mortgage locks a lower payment and puts you on title now: FHA assumable homes, VA assumable homes.
| Line | Typical in Lakewood | Refundable? | Credited to the price? |
|---|---|---|---|
| Option fee | 1% to 5% of the agreed price | No | Yes, at closing |
| Rent premium | $150 to $500 a month above market rent | No | Yes, as the rent credit |
| Rent credit | 10% to 30% of each payment | No | Yes, if you buy |
| Security deposit | One month | Yes, under Colorado landlord-tenant law | No |
| Maintenance | Routine repairs on you; major systems on the owner | n/a | No |
| Purchase price | Fixed the day you sign | n/a | n/a |
| Rent-to-own | Buy now with FHA + down-payment help | Keep renting | |
|---|---|---|---|
| Cash up front | 1% to 5% option fee | 3.5% down, part of it from CHFA or metroDPA | Deposit |
| Credit needed | 580 to 620 | 580 for FHA | Varies |
| Price locked? | Yes | Yes, you own it | No |
| Equity while you wait | Only the credits | All of it | None |
| Risk | Losing the fee if you cannot close | Normal ownership risk | Rent increases |
| Best for | Mortgage 12 to 24 months away | Score 580+, reserves in hand | Moving in under two years |
Compare the year-one payment with a seller credit toward the rate: seller concessions for buyers and can I afford a home now. First-time buyers: the Colorado first-time buyer guide and what closing costs are in Colorado. Buyers with a home to sell: who is buying at 7 percent.
Every city page below carries the live rent-to-own and lease-option listings, the requirements, the costs, and the questions buyers ask there.
Usually, yes. A 620 score and two years of steady income qualify for Colorado down-payment programs, and a participating lender’s $1,000 cash-to-close program pairs the assistance with a seller credit so the buyer’s own cash is about $1,000. You own the home from day one instead of paying an option fee for the right to buy it later, and you skip close to two months of rent before the first mortgage payment.
You lease the home for one to three years under a written option to buy it at a price set today. You pay an option fee of 1 to 5 percent of the price up front, a monthly rent that is a little above market, and part of that rent is credited toward the purchase. At the end of the term you buy with a normal mortgage, using the credits and the option fee as part of the down payment, or you walk away and forfeit them.
No legitimate one. A seller who skips the credit check is either pricing the risk into a high option fee and rent, or running a scam. Expect a soft pull at the application and a full pull when you exercise the option and apply for the mortgage.
The option fee, 1 to 5 percent of the agreed price: $5,000 to $25,000 on a $500,000 home. It is non-refundable if you do not buy, and it is credited to the price if you do. Compare that with 3.5 percent down on an FHA purchase, which buys the home outright today.
A lease-option gives you the right, not the obligation, to buy; you can walk away and lose the fee and credits. A lease-purchase obligates you to buy at the end of the term, and the seller can sue for the difference if you cannot close. Sign a lease-option unless a Colorado real estate attorney has read the lease-purchase and told you why it is sound for you.
Yes. Colorado has no single rent-to-own statute; the deal runs under landlord-tenant law and real estate contract law, and the Colorado Real Estate Commission requires the purchase-option contract to be drafted by a licensed attorney rather than a broker. Colorado does not require the option to be recorded, so ask for a recorded memorandum of option to protect your position if the seller sells or refinances.
Whatever the contract says. Most Colorado lease-options put routine maintenance on the tenant-buyer and keep taxes, insurance and major systems with the owner until closing. Get a home inspection before you sign, the same as a purchase, and write the roof, furnace and sewer line into the agreement.
Run both numbers. Colorado buyers with a 580 to 620 score and three months of reserves can buy today with FHA and a down-payment program such as CHFA or metroDPA, and a seller credit toward the rate. Rent-to-own only wins when the mortgage is 12 to 24 months away and the home is worth locking in at today's price.
Yes, as long as the HOA allows leasing and the owner holds clear title. Condos also need the building to be FHA-eligible if you plan to buy with FHA at the end; check the approval list before you pay an option fee.
Two months of pay stubs or a year of bank statements if self-employed, two years of W-2s or tax returns, a photo ID, the last two months of bank statements for the option fee, and your rental history. A seller who asks for a fee before showing you the home or the contract is a red flag.
Call or text 303-955-4220. A live person sends both within one business day: the sellers who will write a lease-option, and what you qualify for today.
Call or text 303-955-4220All Colorado rent-to-own homesThe cheapest Lakewood homes, on a map: 146 homes under $400,000 and 93 under $300,000 this week, with the HOA on every tile and the programs that bring your cash to about $1,000: affordable homes for sale in Lakewood. Statewide: affordable homes in Colorado.
Disclaimer: The Kenna Group at Keller Williams DTC are real estate agents, not lenders, mortgage brokers or credit counselors. Credit scores, loan and assistance rules on this page are general information as of October 25, 2026, and programs change; a licensed lender of your choice confirms what you qualify for, and a HUD-approved housing counselor can help with credit and budgeting. Nothing here is legal advice: have a Colorado real estate attorney review any lease-option or lease-purchase contract before you sign.