
Rent to own homes in Westminster are private lease options with sellers; the City of Westminster has no rent-to-own program, and its own down payment program is listed as coming soon. On October 25, 2026, 1 of the 328 Westminster homes for sale mentioned rent to own, a lease option or seller financing in the MLS remarks, and the grid below shows Westminster homes for sale now. CHAC, CHFA and metroDPA already lend in Westminster, so a 620 score may be enough to buy.
Get rent-to-own and low-down-payment homes in Westminster sent to you. Call or text 303-955-4220. A live person answers.
Send me the Westminster listWhat it’s like to live in Westminster: our Westminster area guide.

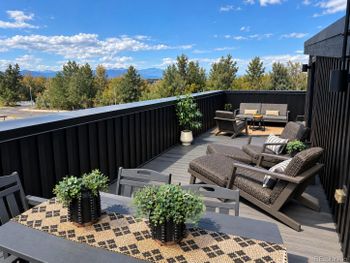
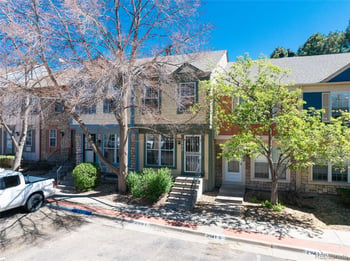
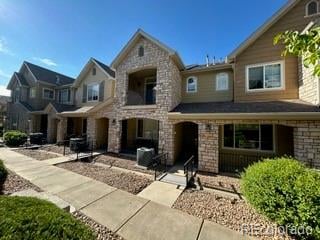
Westminster has one of the smallest rent-versus-own gaps on our list: a $1,882 Census median rent against a $2,252 median owner cost with a mortgage. When owning costs only about $370 more a month, a Westminster lease to own fee is hard to justify unless a loan is 12 to 24 months away. The Kenna Group at Keller Williams DTC asks first: what has you looking at rent-to-own instead of buying?
620+
You may not need rent-to-own. CHFA, CHAC and metroDPA all lend in Westminster. Next step: a pre-approval call with a lender of your choice.
580 to 619
Buy with your own down payment. 580 is the FHA minimum with 3.5% down, about $18,550 on a $530,000 Westminster home. Most down payment assistance programs we work with start at a 620 credit score, so this path uses your own savings.
Under 580
Work on credit first. A lender call will not help yet. Pull your free reports at annualcreditreport.com and ask us about the Kenna Credit Care program; we call back when the score is ready.
| Rent to own (lease option) | Buy now with down payment assistance | |
|---|---|---|
| Cash up front | Option fee, often 1% to 5% ($5,300 to $26,500), lost if you do not buy | CHFA asks for at least $1,000 of your own money; CHAC lends 6% of the price up to $12,000; the seller credit sets the rest |
| Credit | Set by each seller; you still need a mortgage when the lease ends | 620 for most assistance; 580 with your own 3.5% FHA down payment |
| Who owns the home | The seller, until you close | You, at closing |
| Equity while you wait | Only the rent credits the contract allows | All of it, from day one |
| Which homes | Only homes whose sellers agree to a lease option | Any Westminster home for sale: the whole grid above |
The $530,000 example is near the Census median Westminster value ($532,400); today’s average list price is $538,000. The 2026 FHA and conforming limit in Adams and Jefferson counties is $862,500.
Checking a Westminster seller: Westminster spans Adams and Jefferson counties, so check the right one: Adams County property search and recorded documents, or Jefferson County property search and land records.
328
Westminster homes for sale, active or coming soon, October 25, 2026
84
of them listed at $400,000 or less
1
mention rent to own, a lease option or seller financing in the MLS remarks
84 of the 328 Westminster listings are at $400,000 or less. Starter search: affordable homes for sale in Westminster.
No. The city lists CHFA, CHAC, metroDPA and Elevation Community Land Trust as buyer resources, and its own down payment program was still listed as coming soon in October 2026. Rent-to-own in Westminster is a private lease option.
On October 25, 2026, 1 of the 328 Westminster homes for sale mentioned rent to own, a lease option or seller financing in the MLS remarks.
The city’s October 6, 2026 town hall listed down payment assistance under programs coming soon, without terms. Until it opens, CHFA, CHAC and metroDPA are the options.
Westminster is in Adams and Jefferson counties. Look the address up in the right county’s property search, then its recorded documents for loans and liens, before any option fee.
Census 2020-2024 figures show a median rent of $1,882 and a median owner cost with a mortgage of $2,252, about $370 apart. A rent-to-own deal adds an option fee and often a rent premium.
Next steps: Westminster homes for sale · CHFA down payment assistance · the $1,000 cash-to-close path · mortgage pre-approval · first-time buyer guide · Denver rent to own homes · Thornton rent to own homes · Broomfield rent to own homes · all Colorado rent to own homes · our Westminster area guide.
Call or text 303-955-4220. A live person answers.
Browse Available Homes
Search "rent to own homes Westminster" and most of what comes back is a list-building site that wants a fee. The real Westminster inventory is the grid above: homes whose sellers will write a lease-option, plus the ones we ask on your behalf once they have sat past 45 days. The Westminster listings carrying a lease-option or seller-financing note this week are land and commercial, not houses, so the residential deals are made by asking the sellers of homes past 45 days. Below: the requirements, the costs, the Colorado contract rules, the red flags, the other Front Range cities, and the buy-now path.
The deal
1 to 3 years
Option fee of 1 to 5 percent up front, part of the rent credited to the purchase.
What sellers want
580 to 620
No eviction or bankruptcy in the last two years. Below 580, a 12-month repair plan first.
The alternative
3.5% down
Many rent-to-own shoppers can buy today. A live person runs both numbers.
The rule
Attorney + recorded
Colorado has no rent-to-own statute; the contract is the protection.
Most people searching for rent-to-own in Westminster can buy a home now. A 620 credit score qualifies for Colorado down-payment assistance, and a participating lender can run a program that brings the buyer’s cash to close to about $1,000: the down payment comes from the assistance, the closing costs come from the seller credit, and you keep the money a rent-to-own seller would have taken as an option fee. There is a second saving nobody mentions: the first mortgage payment is not due until the first of the month after the month you close, so a buyer who closes early in the month skips close to two months of rent on the way in.
Nearly everyone typing rent to own Westminster into a phone is a renter who wants to own and believes one thing blocks it: the down payment, the score, the debt, a new job or an old foreclosure. Westminster has 385 homes for sale this week and 139 of them are under $475,000; each of those blocks has a fix that costs less than a lease-option. The charts use the median Westminster home at $520,000 and a 30-year FHA loan.
Every Westminster home for sale: Westminster homes for sale. Call or text 303-955-4220. A live person answers.
The reason most Westminster renters land on a rent-to-own ad, and the easiest one to fix. CHFA puts up to 3 percent of the loan as a grant you never repay, or 4 percent as a 0 percent second mortgage ($20,072 on the median Westminster home), and we write the offer with the seller paying your closing costs. Your own money: about $1,000. The program is on CHFA down payment assistance in Colorado; the worked example on $1,000 cash to close.
FHA closes at 580 with 3.5 percent down and at 500 with 10 percent. From 580 to 619 you buy with FHA and skip the assistance; under 580 you spend 60 days on credit care and come back. The Westminster homes: Westminster homes that pass FHA.
FHA approves total debt up to 50 percent of income with a 620 score, and it counts an income-based student loan payment as it is paid. On a $70,000 income that leaves about $2,300 for the Westminster house payment after $600 of other bills. Run yours on mortgage pre-approval.
A salaried job in the same field closes with an offer letter and one pay stub; a self-employed buyer brings two years of returns. A lender who works with self-employed buyers can read a Westminster file in a day: pre-approval.
FHA waits three years after a foreclosure or short sale, two after a Chapter 7, one year of Chapter 13 payments. Inside that window a Westminster lease-option bridges to the date; past it you buy. The homes and the timeline: after a foreclosure.
Then a two-year lease-option is the right tool: the option fee is the only money at risk, and buying then selling inside two years costs about 8 percent of the price. Nearby options: Arvada, Thornton, Wheat Ridge, Northglenn.
That is the ad for a scam. A real Westminster lease-option is drafted by a lawyer, recorded against the title, and signed with a seller whose loan is current. The red flags are listed below.
A lease-option locks the price above today's market. The cheaper lock in Westminster is an assumable 3 percent FHA or VA loan: Colorado assumable mortgage homes and VA assumable homes.
| Line | Typical in Westminster | Refundable? | Credited to the price? |
|---|---|---|---|
| Option fee | 1% to 5% of the agreed price | No | Yes, at closing |
| Rent premium | $150 to $500 a month above market rent | No | Yes, as the rent credit |
| Rent credit | 10% to 30% of each payment | No | Yes, if you buy |
| Security deposit | One month | Yes, under Colorado landlord-tenant law | No |
| Maintenance | Routine repairs on you; major systems on the owner | n/a | No |
| Purchase price | Fixed the day you sign | n/a | n/a |
| Rent-to-own | Buy now with FHA + down-payment help | Keep renting | |
|---|---|---|---|
| Cash up front | 1% to 5% option fee | 3.5% down, part of it from CHFA or metroDPA | Deposit |
| Credit needed | 580 to 620 | 580 for FHA | Varies |
| Price locked? | Yes | Yes, you own it | No |
| Equity while you wait | Only the credits | All of it | None |
| Risk | Losing the fee if you cannot close | Normal ownership risk | Rent increases |
| Best for | Mortgage 12 to 24 months away | Score 580+, reserves in hand | Moving in under two years |
Compare the year-one payment with a seller credit toward the rate: seller concessions for buyers and can I afford a home now. First-time buyers: the Colorado first-time buyer guide and what closing costs are in Colorado. Buyers with a home to sell: who is buying at 7 percent.
Every city page below carries the live rent-to-own and lease-option listings, the requirements, the costs, and the questions buyers ask there.
Usually, yes. A 620 score and two years of steady income qualify for Colorado down-payment programs, and a participating lender’s $1,000 cash-to-close program pairs the assistance with a seller credit so the buyer’s own cash is about $1,000. You own the home from day one instead of paying an option fee for the right to buy it later, and you skip close to two months of rent before the first mortgage payment.
You lease the home for one to three years under a written option to buy it at a price set today. You pay an option fee of 1 to 5 percent of the price up front, a monthly rent that is a little above market, and part of that rent is credited toward the purchase. At the end of the term you buy with a normal mortgage, using the credits and the option fee as part of the down payment, or you walk away and forfeit them.
The listings on this page are the Westminster homes whose sellers accept a lease-option, lease-purchase or seller-financing structure, pulled live from the MLS. Most rent-to-own deals in Colorado are private agreements with an individual seller, not a program, so the inventory changes weekly. Call or text 303-955-4220 and a live person checks the current list, including the homes not marked that way in the MLS.
Yes, that is what the structure is for. Most sellers want a score of 580 to 620, income of about three times the monthly rent, and no eviction or bankruptcy in the last two years. Below 580 the plan is a 12-month lease with a credit-repair schedule, then the option. An FHA loan needs 580 with 3.5 percent down, so many buyers who think they need rent-to-own can buy now.
No legitimate one. A seller who skips the credit check is either pricing the risk into a high option fee and rent, or running a scam. Expect a soft pull at the application and a full pull when you exercise the option and apply for the mortgage.
The option fee, 1 to 5 percent of the agreed price: $5,000 to $25,000 on a $500,000 home. It is non-refundable if you do not buy, and it is credited to the price if you do. Compare that with 3.5 percent down on an FHA purchase, which buys the home outright today.
Not if the option is written correctly: the price is fixed the day you sign, and the option binds the seller for the term. Recording a memorandum of option puts the world on notice. An unrecorded option and a seller with a mortgage in default is how buyers lose their option fee.
No. The national lease-with-right-to-purchase programs stopped taking applications, and the last one sold in 2025. Every rent-to-own deal in Westminster today is a private agreement with an individual seller, which is why the listings here come straight from the MLS and why the $1,000 cash-to-close path beats most of them.
With a lease-option you move out and forfeit the option fee and rent credits. With a lease-purchase you are in breach. That is why the plan starts with a lender: a pre-approval path with a date, so the option term matches the time it takes to fix the credit or save the difference.
Run both numbers. Colorado buyers with a 580 to 620 score and three months of reserves can buy today with FHA and a down-payment program such as CHFA or metroDPA, and a seller credit toward the rate. Rent-to-own only wins when the mortgage is 12 to 24 months away and the home is worth locking in at today's price.
Call or text 303-955-4220. A live person sends both within one business day: the sellers who will write a lease-option, and what you qualify for today.
Call or text 303-955-4220All Colorado rent-to-own homesThe cheapest Westminster homes, on a map: 76 homes under $400,000 and 42 under $300,000 this week, with the HOA on every tile and the programs that bring your cash to about $1,000: affordable homes for sale in Westminster. Statewide: affordable homes in Colorado.
Disclaimer: The Kenna Group at Keller Williams DTC are real estate agents, not lenders, mortgage brokers or credit counselors. Credit scores, loan and assistance rules on this page are general information as of October 25, 2026, and programs change; a licensed lender of your choice confirms what you qualify for, and a HUD-approved housing counselor can help with credit and budgeting. Nothing here is legal advice: have a Colorado real estate attorney review any lease-option or lease-purchase contract before you sign.