New - 15 Hours Ago

$807,500
Coming Soon
5
Beds
3
Baths
3981
Sqft
2.56
Acres
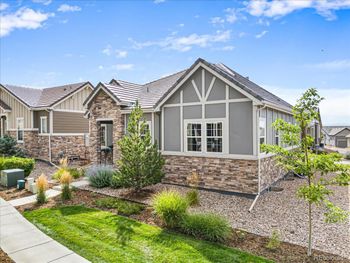
265 Saddlehorn Trl, Monument, CO 80132
MLS#: 8325178
Kenna Real Estate Group · Moving a parent closer in Colorado
Buying a home for an aging parent in Colorado works three ways: you buy it at an owner-occupied rate under the Fannie Mae parent rule, you cosign your parent's FHA loan, or your parent buys with a reverse mortgage and no payment. Here is each route priced on a $450,000 home, and the next-gen, in-law suite and 55+ options that fit.
A live person answers. Not a robot, not a phone tree.
The Fannie Mae parent rule: a home for a parent who cannot qualify on their income counts as your principal residence. 5 percent down, no investor surcharge, you do not live there.
FHA takes a relative as a non-occupant co-borrower at 3.5 percent down. The loan is in both names; your income fills the gap.
A reverse mortgage for purchase at 62 and up funds about half the price. Sale proceeds from the old house cover the rest.
A second front door, kitchen and laundry inside one house, or a finished wing. One mortgage, two households.
Allowed on detached-home lots across the Front Range metro areas under the state ADU law. $200,000 to $300,000 new in Denver.
Two households, a social calendar for the parent, and the lowest price of the six.
The route is decided by two numbers: the parent's income and the equity in the parent's current home. A parent with a pension and a paid-off house takes route 3 and never makes a payment. A parent with Social Security alone takes route 1 or 2 with you on the loan. Mike Oswald at Rate, a lender many of our buyers use, prices all three on the same afternoon; the parent's home gets the Smart Pricing Report on home valuation the same day.
Many of our buyers use Mike Oswald at Rate and trust him. The Kenna Real Estate Group is not affiliated with Rate or Mike Oswald, you are free to use any lender you choose, and we receive nothing for the introduction. Mike Oswald, NMLS 261003 · Rate, Inc., NMLS 2611 · Equal Housing Lender.
The parent rule wins on cash and payment for a buyer with the income to carry two homes. The FHA co-borrower route wins when the parent has some income and you want the loan in the parent's name. The reverse mortgage wins when the parent is selling a paid-off house and wants no payment for life; the money that does not go into the new home stays in the bank for care. The sale that funds it is on selling a parent's house in Colorado.
Private entrance, bedroom, bath, kitchenette and laundry under the main roof, built that way by Lennar, Richmond American and Toll Brothers across the Front Range. One loan, one tax bill, and the parent is 30 feet away. Colorado next-gen homes; by city: Aurora, Thornton, Colorado Springs, Parker, Castle Rock, Fort Collins.
A walkout basement or a main-floor bedroom wing with its own bath, $60,000 to $120,000 to build, or already there in the listings on Colorado in-law suite homes and multigenerational homes. Main-floor suites matter most: no stairs for the parent.
Its own kitchen, bath and address. Colorado's ADU law requires the Front Range metro cities to allow one on every detached-home lot; Denver, Aurora, Lakewood and Fort Collins already permit them. Listings on homes with an ADU; rules on the Denver zoning and ADU guide.
One-level homes with a main-floor suite, and the 55+ communities ten minutes from the Front Range cities where the grown sons and daughters live: Colorado ranch and patio homes, Colorado 55+ communities, the 55+ map with homes for sale, Denver homes with an ADU, Aurora multigenerational homes, Arvada homes with an ADU, Colorado Springs multigenerational homes, Fort Collins homes with an ADU, Greeley patio homes, Loveland patio homes, Littleton patio homes, Parker patio homes. The stair-free checklist is on the Colorado one-level home checklist.
Yes. Fannie Mae lets you buy a home for a parent who cannot qualify on their own income and treat it as your principal residence: 5 percent down, owner-occupied rates, no second-home or investment surcharge, and you do not live there. The parent's income is not on the loan; yours carries both payments. The ratio run is on mortgage pre-approval.
Yes. FHA allows a relative as a non-occupant co-borrower at 3.5 percent down, so the loan is in your parent's name and yours, your parent lives there, and your income fills the gap. Conventional allows it at 5 percent down. The trade: the payment sits on your credit report until the loan is paid or refinanced. FHA rules are on FHA and VA home buying; the side-by-side on FHA vs conventional.
Move them when the care is coming from you and your work is here: a parent ten minutes away in a 55+ patio home or a next-gen suite costs less in time and money than two households 600 miles apart. Move toward them when their doctors, friends and the paid-off house are all there and the care is years off. Either way the first number is what their house sells for: selling a parent's house in Colorado.
Yes. Under the parent rule the parent contributes what they can and no lease is required; under the investment route a written lease at market rent is required and the rent counts as your income. The parent rule is cheaper in cash and rate, and the parent's contribution still offsets the payment. The investment math is on the rental property checklist.
A loan for buyers 62 and older that funds about half the price of the new home with no monthly payment; the balance comes due when the owner moves out or passes. A parent selling a paid-off $500,000 home and buying a $450,000 patio home puts about $250,000 down, keeps about $200,000 after costs, and owes nothing each month.
A next-gen home has a second front door, kitchen and laundry inside one house, and the builders price it as one home: the simplest answer when everyone moves. An in-law suite is a finished basement or main-floor wing in an existing home, $60,000 to $120,000 to build. A detached accessory dwelling unit is its own small house in the backyard, $200,000 to $300,000 new in Denver, allowed on detached-home lots across the Front Range metro areas under the state ADU law. Listings: next-gen homes, in-law suite homes, homes with an ADU; the Denver rules on the Denver zoning and ADU guide.
About 5 to 8 percent more than the same house without one in the Denver metro, and they sell faster, because every buyer with an aging parent or an adult son or daughter at home is hunting the same 300 listings. The suite also rents: a legal basement apartment in Denver carries $1,400 to $1,900 a month, which covers most of the premium. Search by city: Denver, Aurora, Arvada, Colorado Springs, Fort Collins.
When the parent is active and wants a social calendar, yes: a patio home in a 55+ community ten minutes from you costs less than a next-gen home and keeps two households. Dues, age rules and resale limits are on 55+ rules, dues and resale in Colorado; every community with homes for sale is on the Colorado 55+ communities map.
No steps from the garage or the front door, a bedroom and full bath on the main level, 36-inch doorways, a shower with no curb, and a laundry on the same floor. The checklist is on the Colorado one-level home checklist; the homes on Colorado ranch and patio homes.
The home a parent lives in is exempt from Medicaid asset counting in Colorado up to the state equity limit, and the care itself costs $6,000 to $9,000 a month for in-home or assisted care on the Front Range, which is the number that decides whether the parent sells, moves in, or buys with a reverse mortgage. The worksheet is on the Colorado care-funding worksheet.
Sell when the equity is needed for the next home or the care, and the house is more than 20 years old; rent it when the mortgage is gone, the roof and furnace are under 10 years old, and the parent has other money for the move. The Smart Pricing Report on home valuation gives the sale number.
If it is in your name under the parent rule, nothing changes. If it is in the parent's name, it passes by the will or by Colorado probate, which takes six to twelve months when nobody planned. The steps are on the Colorado inherited-home checklist and the Colorado probate seller checklist.
Text PARENT and the city to 303-955-4220. A live person answers, runs the parent rule, the co-borrower route and the reverse-mortgage route with your lender the same day, and sends the next-gen and one-level homes in that city.