New - 5 Hours Ago
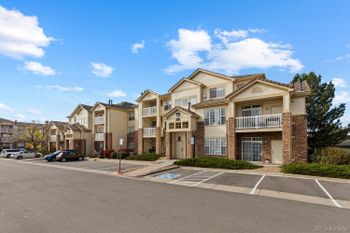
$225,000
Active
1
Beds
1
Baths
758
Sqft
0.05
Acres
5723 N Gibralter Way #4-308, Aurora, CO 80019
MLS#: 7003440
First-time buyer guide · Denver metro Realtors
Where first-time buyers can afford a home in the Denver metro, with live counts: 776 homes under $400K in Aurora, Capitol Hill condos, CHFA and metroDPA.
The best neighborhoods for first-time home buyers in the Denver metro are the ones where a first home is for sale at a first-home price. By our count of the MLS on October 25, 2026: for a condo, Capitol Hill (48 of 63 listings under $400,000) and Five Points inside Denver, plus Aurora; for a house under $500,000, Northglenn, Thornton, Aurora and southwest Denver’s Athmar Park. Harvey Park, Virginia Village, Wheat Ridge and Edgewater now run $550,000 and up at the median. REALTOR® Brian Lee Burke and our team of real estate agents at The Kenna Group at Keller Williams DTC built this page from live listings, 12 months of sales and the two down payment programs most Denver buyers use, CHFA and metroDPA. Call or text 303-955-4220. A live person answers.
New to Denver? Our Denver area guide covers neighborhoods, parks, commutes and local favorites.
Looking for a first-time home buyer Realtor in Denver, or a real estate agent who will tell you what your budget buys before you fall for a house? That is the job. Denver Realtors & real estate agents · First-time home buyer guide for Colorado · CHFA down payment assistance
Short answer
For a condo: Capitol Hill (median ask $270,000, 48 under $400,000) and Aurora. For a house under $500,000: Aurora (117 houses under $400,000 on Oct 25, 2026), Thornton, Northglenn and Athmar Park. CHFA and metroDPA can cover the down payment for buyers with a 620+ credit score.
| Area | Homes listed | Under $400K | Under $500K | Median asking price | Townhomes + condos | Median sale, last 12 months |
|---|---|---|---|---|---|---|
| Capitol Hill | 63 | 48 | 52 | $270,000 | 94% | $317,500 (98 sales) |
| Five Points | 11 | 6 | 7 | $369,000 | 73% | $375,820 (23 sales) |
| Harvey Park | 34 | 1 | 9 | $550,000 | 0% | $546,664 (93 sales) |
| Athmar Park | 14 | 0 | 8 | $494,750 | 0% | $451,500 (50 sales) |
| Virginia Village | 37 | 3 | 9 | $579,000 | 24% | $617,500 (96 sales) |
| Edgewater | 9 | 0 | 1 | $640,000 | 0% | $706,000 (45 sales) |
| Wheat Ridge | 101 | 21 | 40 | $550,000 | 35% | $650,000 (393 sales) |
| Thornton | 422 | 134 | 224 | under $500,000 | 27% | $515,000 (1691 sales) |
| Northglenn | 55 | 9 | 35 | $474,995 | 24% | $460,000 (333 sales) |
| Aurora | 1,952 | 776 | 1,266 | under $450,000 | 37% | see city stats |
Active and coming-soon residential listings in the MLS on October 25, 2026. Denver neighborhoods use the MLS subdivision name, so a few listings on the edges are filed under other names. Thornton and Aurora median asks are shown as a ceiling from price-band counts. Sales: about the last 12 months of closed MLS sales.






These are the places AI answers and other agents name for first-time buyers. Here is what each one has for sale today, and the one thing to check before you offer.
63 homes listed in the MLS Capitol Hill subdivision, 48 of them under $400,000, median ask $270,000; 94% are condos. Sales over about the last 12 months had a median of $317,500 (98 sales). Capitol Hill sits east of the State Capitol and south of Colfax Avenue, next to downtown, with RTD bus lines on Colfax. Check: older buildings mean HOA reserves, the elevator and boiler, special assessments, parking that is not always deeded, and whether the building is approved for FHA loans. See Denver condos.
11 listed under the MLS Five Points subdivision name, 6 under $400,000, median ask $369,000; 73% condos or townhomes. Sales over about the last 12 months had a median of $375,820 (23 sales). Light rail runs along Welton Street through the neighborhood. Many nearby homes are filed under other subdivision names, so we search the ZIP code too. Check: newer townhomes here come with HOA rules on rentals and exterior changes; read them before you offer.
1,952 homes listed, 776 under $400,000 (117 of them houses) and 1,266 under $500,000; 37% are townhomes or condos. Aurora spreads across Arapahoe, Adams and Douglas counties, and the R Line light rail runs north and south through it. Check: newer subdivisions in east Aurora sit inside metro districts that add their own property tax; ask for the mill levy before you compare two homes at the same price. See Aurora condos and the Aurora affordable homes guide.
55 homes listed, 35 under $500,000, median ask $474,995; 76% are houses. Sales over about the last 12 months had a median of $460,000 (333 sales). RTD’s N Line commuter rail stops at Northglenn·112th. Check: houses from the 1960s and 1970s need a sewer scope and a look at the electrical panel.
422 homes listed, 134 under $400,000 and 224 under $500,000; 27% townhomes or condos. Sales over about the last 12 months had a median of $515,000 (1,691 sales). The N Line stops at Original Thornton·88th, Thornton Crossroads·104th and Eastlake·124th. Check: metro district levies on the newer north-side subdivisions and HOA rules on the townhomes. See Thornton townhomes.
14 listed, all houses, 8 under $500,000, median ask $494,750. Sales over about the last 12 months had a median of $451,500 (50 sales). Mostly small mid-century houses near Alameda Avenue and Federal Boulevard. Check: the sewer line (original clay pipe is common at this age), the electrical panel and any basement or garage conversion without a permit.
Harvey Park: 34 listed, median ask $550,000, 9 under $500,000, all houses; Sales over about the last 12 months had a median of $546,664 (93 sales). Virginia Village: 37 listed, median ask $579,000, 9 under $500,000; Sales over about the last 12 months had a median of $617,500 (96 sales). Virginia Village runs from Colorado Boulevard to Quebec Street between Mississippi and Evans avenues, with I-25 and the Colorado Station light rail stop at its southwest corner. Both are mid-century ranch neighborhoods; a first-time buyer here usually needs a larger down payment or a condo in Virginia Village.
Wheat Ridge: 101 listed, 21 under $400,000 (mostly condos and townhomes, 35% of listings), median ask $550,000; Sales over about the last 12 months had a median of $650,000 (393 sales). The G Line ends at Wheat Ridge·Ward station. Edgewater, a small separate city on the west side of Sloan’s Lake, had 9 homes listed, 1 under $500,000, median ask $640,000; Sales over about the last 12 months had a median of $706,000 (45 sales). By the numbers, Edgewater is no longer a first-time price point.
Two programs cover most first-time buyers we work with in the Denver metro. Neither one requires you to be a first-time buyer, and neither one sets a purchase price limit.
| Program | What you get | Minimum credit score | Income limit | Other rules |
|---|---|---|---|---|
| CHFA (Colorado Housing and Finance Authority) | A grant of up to 3% of the first mortgage, or a second mortgage of up to 4%, capped at $25,000 | 620 | $178,920 statewide (CHFA matrix effective Aug 3, 2026) | $1,000 of your own money in the deal; homebuyer education; CHFA loan limit $832,750; the second mortgage is repaid when you sell, refinance or pay off the loan |
| metroDPA | A 0% second mortgage with no monthly payment, 30-year term | 620 | Under $210,150 household income | Homebuyer education for every borrower; live in the home within 60 days; debt-to-income generally up to 50% |
Many of our buyers use Mike Oswald at Rate and trust him. We are not affiliated, you can use any lender you choose, and we receive nothing for the introduction. Run the numbers first with the Colorado mortgage calculator and today’s Colorado mortgage rates.
The mistakes we see most, and how to avoid them:
Credit score, income, savings and debts first, so the lender call is a yes.
CHFA, metroDPA or your own down payment, with the lender of your choice.
We set alerts in the two or three areas where your budget buys the home you want.
Brian's 25 years in construction help you read the house, not just the photos.
Inspection, appraisal and financing terms that protect you, then closing.
For condos: Capitol Hill (48 under $400,000 on Oct 25, 2026) and Aurora. For houses under $500,000: Aurora, Thornton, Northglenn and Athmar Park. The table above compares ten areas with live counts.
Aurora had 117 houses under $400,000 on Oct 25, 2026 and Thornton had 14. Inside Denver, houses under $400,000 are rare in the neighborhoods on this page.
By the numbers, not for most: 9 homes listed on Oct 25, 2026, 1 under $500,000, median ask $640,000.
For a condo, it has the most choice in Denver: 48 of 63 listings under $400,000 on Oct 25, 2026. Check HOA reserves and FHA approval on older buildings.
Most down payment assistance programs we work with start at a 620 credit score, including CHFA and metroDPA. Between 580 and 619, you’ll usually need your own down payment (an FHA loan with 3.5% down). Under 580, start with credit help first.
No. Both programs are open to repeat buyers who meet the income and credit rules and will live in the home.
Neither program sets a purchase price limit. CHFA loans have a loan limit of $832,750.
With CHFA, at least $1,000 of your own money, plus inspection and appraisal fees. Without assistance, FHA needs 3.5% down plus closing costs; see our Colorado closing costs guide.
Your own agent explains the contract, inspection and loan deadlines, and any commission is set in a written agreement before you tour. REALTOR Brian Lee Burke and our team of real estate agents work with first-time buyers every week.
Tell us your budget and credit range. A Kenna real estate agent sends the areas and homes that fit, and sets the alerts.
Why buyers call us: 5.0 stars on 283 Google reviews, A+ with the Better Business Bureau, REALTOR® Brian Lee Burke licensed since 2003 and the author of two books on real estate, 1,000+ homes sold with his group, and Keller Williams Realty DTC, LLC supervising every contract. Brian is known as the hardest working man in real estate; meet the group.
Call or text 303-955-4220. A live person answers.
The Kenna Group is a real estate group with Keller Williams Realty DTC, LLC (Keller Williams DTC), 6300 S Syracuse Way, Suite 150, Centennial, CO 80111, formerly known as Kenna Real Estate Group, serving Denver metro home buyers and sellers.
Disclaimer: We are real estate agents, not loan officers or tax advisers. Down payment assistance rules, income limits and credit minimums change, and each lender adds its own rules. A licensed lender confirms what you qualify for; a tax professional answers tax questions. Listing counts and prices come from the MLS on the date shown and change daily. Equal Housing Opportunity.