Foreclosure guide
Every Colorado foreclosure, bank-owned (REO) and short sale home on the MLS that you can still buy, live. The Public Trustee timeline and a listing-phrase decoder are under the homes.
Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree.
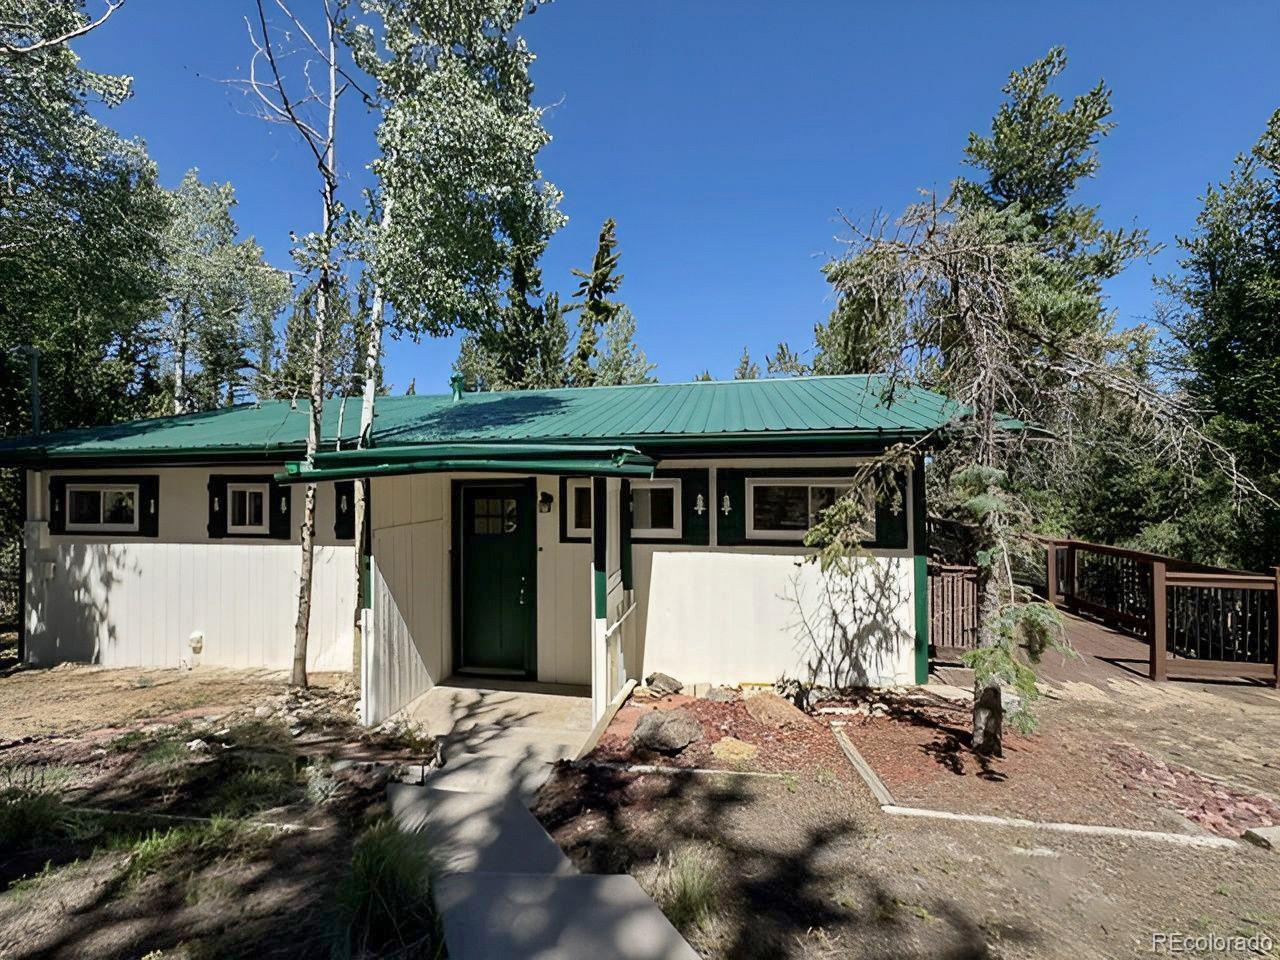
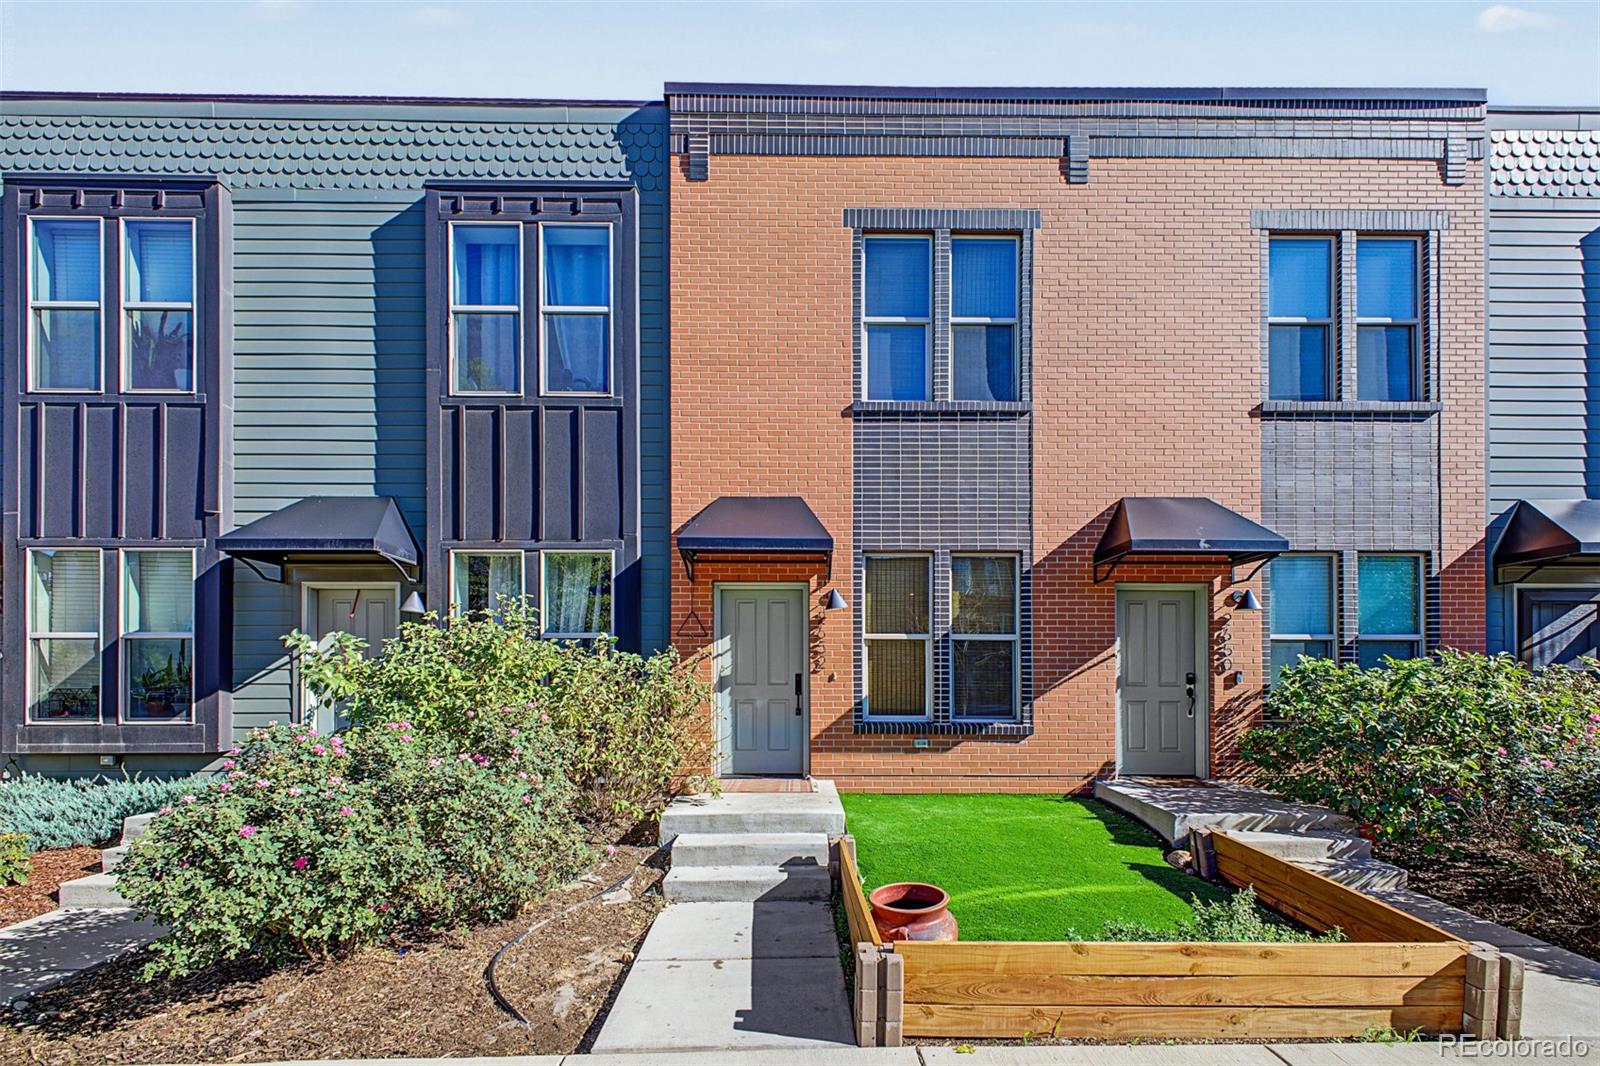
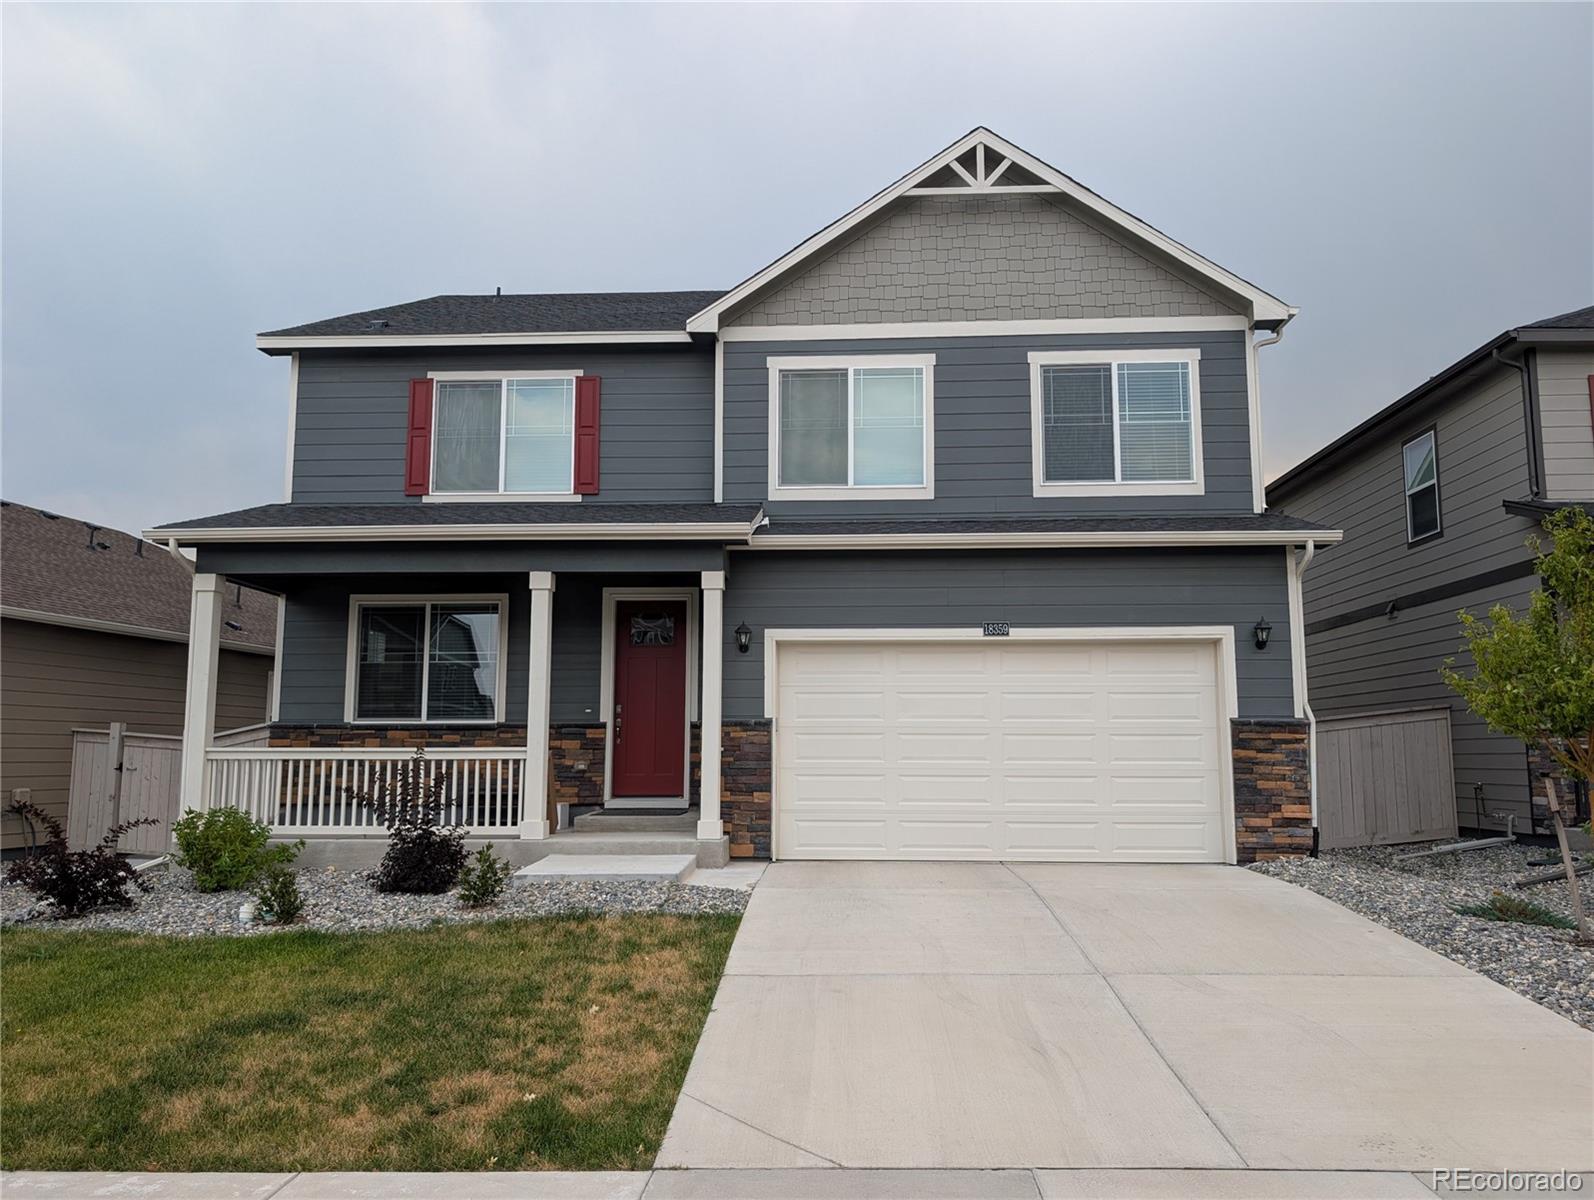

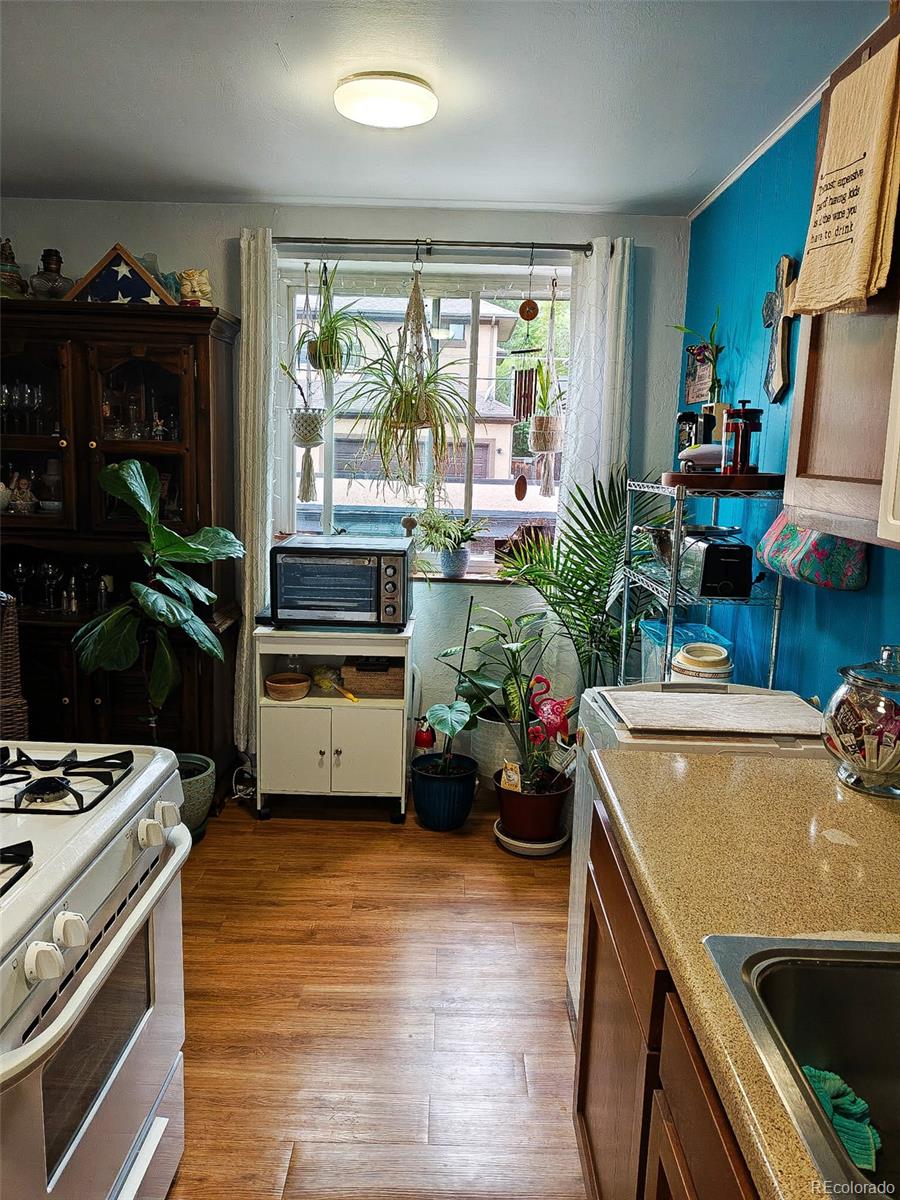
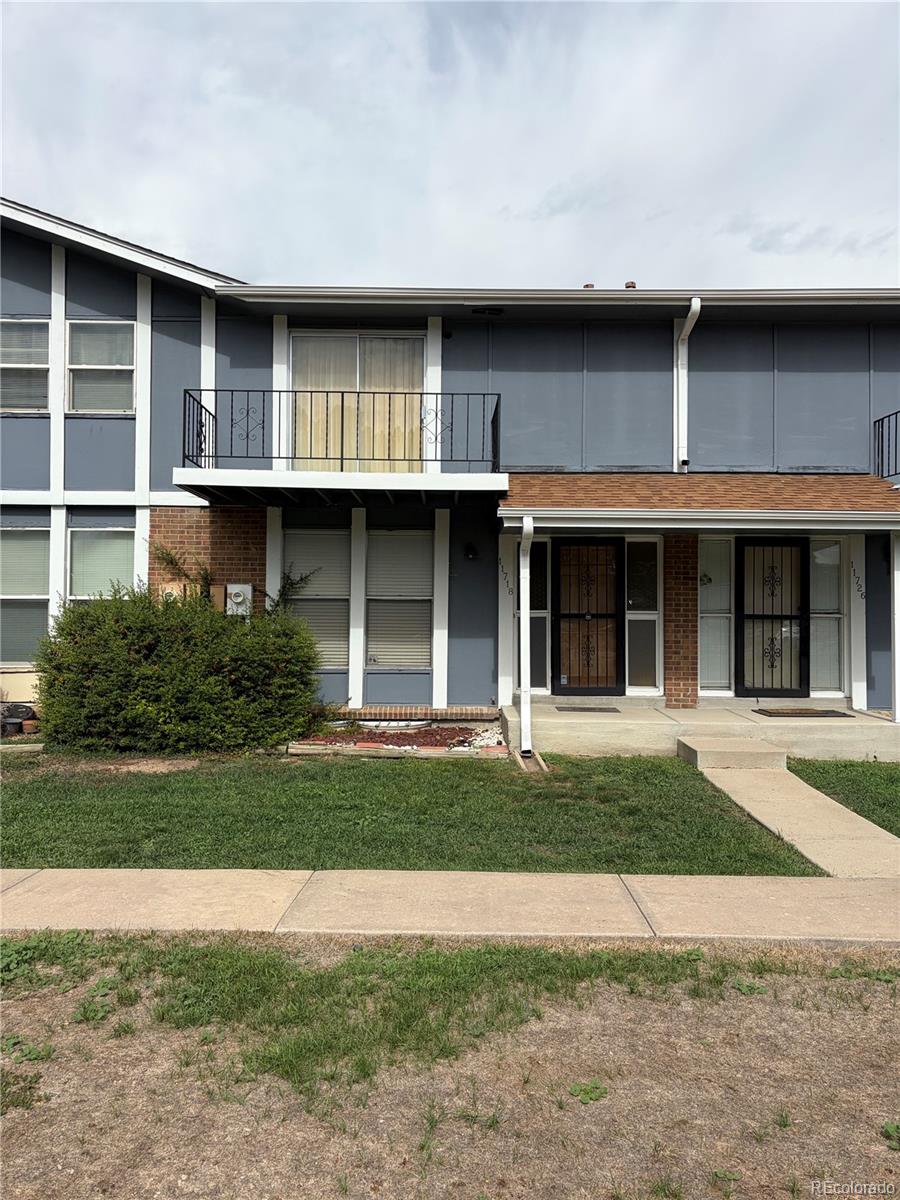

The current owner may still be involved, and Colorado-specific foreclosure protection rules may need review.
The lender or owner after foreclosure may control offer review, addenda, repairs, and deadlines.
Official source, broker requirements, offer process, and condition details need to be checked before relying on the listing.
Colorado forecloses most home loans through the county Public Trustee, not the courts. The clock starts when the lender records a Notice of Election and Demand, and the sale lands 110 to 125 days later. Knowing where a home sits on this clock tells you who you negotiate with and how much time is left.
What this means for a buyer: before the sale, the owner still controls the home, so you buy it as a short sale or a regular sale, and Colorado's Foreclosure Protection Act rules apply to some deals. After the sale, you buy from the bank as an REO. A sale can be postponed, so ask for the current date on any home in foreclosure.
The listing remarks tell you the sale type before you ever call. Each phrase means a different seller, a different inspection and a different loan path.
| Phrase in the listing | Sale type | Who says yes | Inspection | Loans that work |
|---|---|---|---|---|
| "Bank owned", "REO", "lender owned", "corporate owned" | REO (after the foreclosure sale) | The bank's asset manager, using the bank's addendum | Allowed, sold as-is. Utilities are often off; ask the listing agent to turn them on. | Cash and conventional; FHA and VA when the home meets their property standards |
| "Short sale", "subject to lender approval", "third-party approval required" | Short sale (owner still selling) | The owner first, then every lender with a lien on the home | Normal inspection period | Any loan; keep your pre-approval current through a long approval wait |
| "Public Trustee sale", "trustee sale", "auction" | Foreclosure auction | The Public Trustee; highest bidder wins | None; no interior access | Cash or certified funds only |
| "HUD home", "HUD case number", "FHA case" | HUD (government owned) | HUD, through bids on the HUD Home Store | Allowed during the bid period, as-is | FHA, FHA 203(k) and cash; the FHA insurability code decides |
| "HomePath", "Fannie Mae owned" | Fannie Mae REO | Fannie Mae's listing agent and asset manager | Allowed, as-is | Most loans; owner-occupants get a first-look window |
| "Pre-foreclosure", "NED filed", "in foreclosure" | Owner in foreclosure | The owner, before the sale date | Normal inspection period | Any loan; the closing has to beat the sale date |
| "Cash only", "investor special", "will not qualify for financing" | Often REO or a home in rough shape | The seller | Allowed, as-is | Cash or a renovation loan |
Watch out: a listing that says "short sale" can still take two to four months to get the lender's answer. If you have a firm move date, a bank-owned home or a regular sale fits better.
Kenna Real Estate Group does not treat "foreclosure" as one simple search label. The first step is to name the sale type, then check the seller, required forms, property condition, lender requirements, and timing before the price gets too much weight.
Owner-involved foreclosure, bank-owned REO, HUD or agency-owned property, short sale, and auction can each use a different process.
If the current owner is still involved, Colorado Foreclosure Protection Act questions may need broker, managing-broker, or legal review before anyone relies on the deal structure.
Inspection access, utilities, repairs, HOA issues, liens, title questions, and appraisal rules can change whether the listing still makes sense.
A lower list price can be offset by repairs, limited inspection access, utility issues, financing limits, title questions, HOA issues, or extra time. The useful question is not only whether the home looks cheaper. It is whether the process, condition, and lender requirements still work for your plan.
Colorado has foreclosure-specific forms and warnings for some residential foreclosure-related transactions. A broker or attorney should help confirm which contract, notice, and review steps apply before anyone relies on a deal structure.
This page is a buyer guide, not legal advice. Use it to ask better questions before you write an offer or plan around a listing.
The grid at the top covers every Colorado foreclosure and short sale. To narrow it to one sale type or one city, use these pages.
Not always. Foreclosure can refer to a process or sale event. Bank-owned or REO usually means the lender or owner after foreclosure controls the sale. Verify the seller and sale stage.
No. A lower price can be offset by repairs, delays, cash needs, limited access, title questions, or lender requirements. Compare the full cost, not just the list price.
Maybe. The property condition, appraisal result, seller rules, repair limits, and lender guidance decide whether FHA, VA, or another loan type can work for the exact property.
The live grid at the top of this page shows every Colorado foreclosure, bank-owned and short sale home on the MLS. For HUD homes, use the HUD listing page. Call or text 303-955-4220 and we will confirm the sale type on any home.
The Public Trustee sale happens 110 to 125 days after the lender records the Notice of Election and Demand, unless the sale is postponed or the owner cures. The lender cannot make that first filing until the loan is more than 120 days past due.
It is a short sale. The owner accepts your offer first, then the owner's lender has to approve the price. That approval often takes two to four months, and the lender can counter.
Bring the listing, sale type, lender question, timing concern, and condition notes. Kenna can help sort what should be checked before the price carries the decision.
Foreclosure filings in Colorado are up 57% this year and short sales are back. Start with the guide that fits your situation, then search the live inventory by city.
Buying a foreclosure, HUD home or short sale, or selling one? Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree.